Uninsured Driver Case Result
We Recovered $32,500 From Her Own Policy for a Driver Hit From Behind by an Uninsured Driver on I-35E
In 2023, a woman was driving her sedan in the right lane of northbound I-35E, the Stemmons Freeway, when a car hit her from behind in the rain.
The car that hit her carried no liability insurance. Her own uninsured motorist (UM) policy paid its whole $30,000 limit, and her personal injury protection (PIP) added $2,500, for $32,500 in total. No lawsuit was needed.
On This Page
A Rear End Accident in the Rain With a Driver Who Admitted It
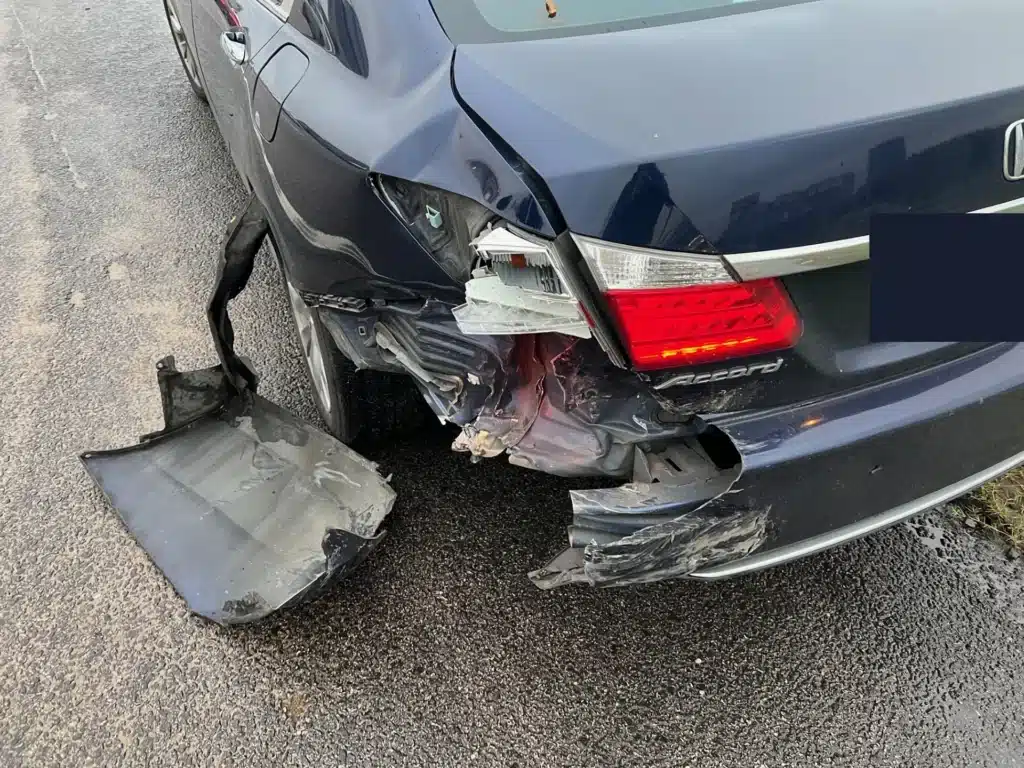
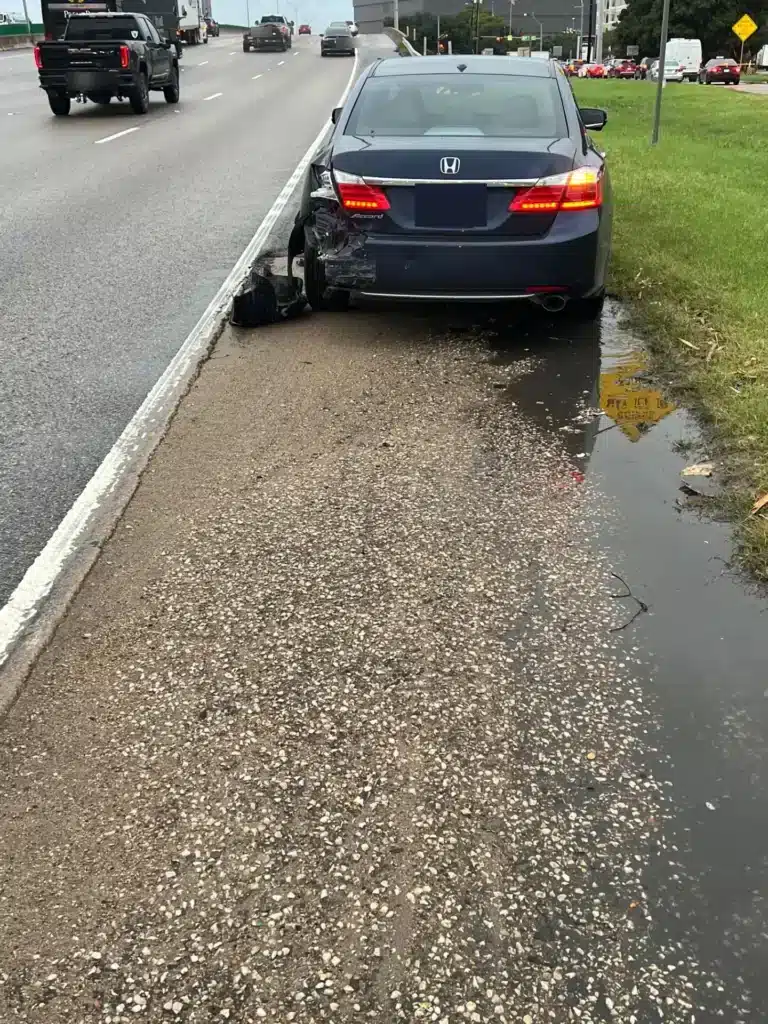
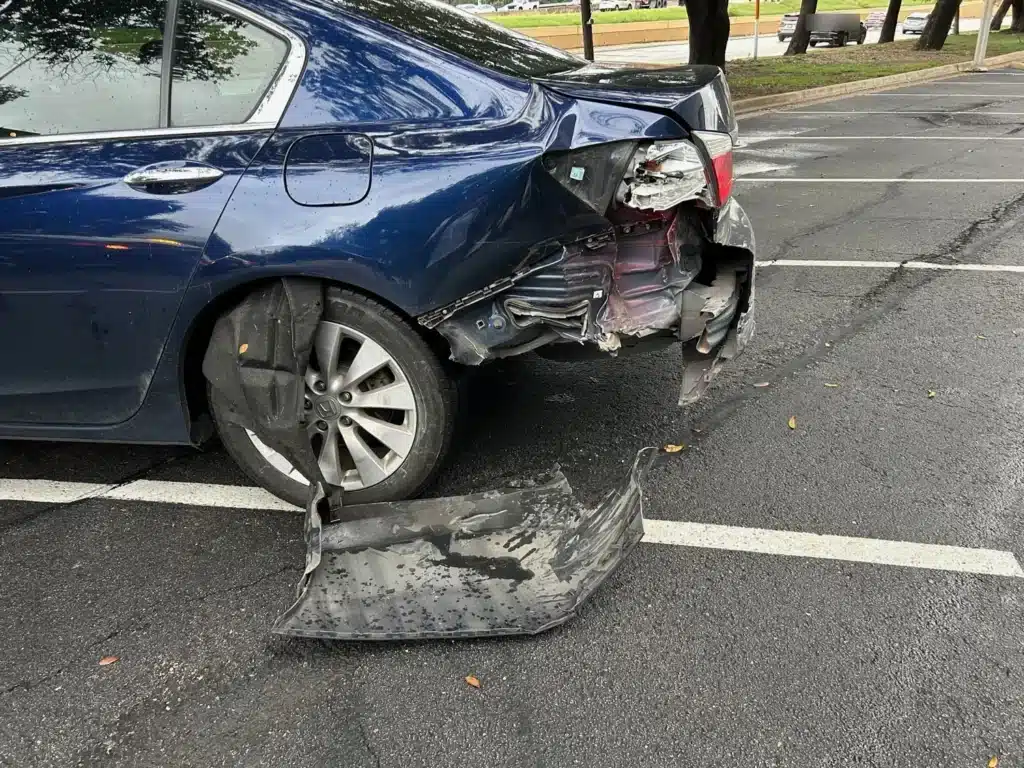
It was about 8 on a weekday morning in 2023. The road was wet, rain was falling, and traffic on northbound I-35E, the Stemmons Freeway, was moving under a 60 mph limit. Our client was in the right lane when a third car came up behind her. It struck the back and left rear corner of her sedan and then the side of another car in the lane beside her. Her rear bumper was torn off, her left rear corner was crushed and the sedan was towed. The Dallas County Sheriff’s Office investigated, and the deputy’s narrative records what the drivers said.
Driver of unit 1 stated that she was traveling in her lane when unit 3 was driving fast and tried to avoid hitting her vehicle but struck her vehicle from behind. […] Driver of unit 3 stated that he was distracted by unit 2 and he could not slow down in time and struck unit 1. I believe the driver of unit 3 was traveling at an unsafe speed and was not paying attention to the roadway.
The report lists the third driver’s factors as “Unsafe Speed” and “Driver Inattention” and shows no proof of insurance for his car. It also lists a charge against him of “No Insurance.” Fault was not in question. The report coded our client’s injury as “C,” a possible injury, and she was not transported from the scene. In 2025 TxDOT records, our rear end crash index found officers cited inattention in 17.9% of the state’s rear end crashes.
A Clear Finding of Fault Does Not Pay a Bill
An admission and a deputy who agrees are strong proof of fault, but proving fault does not pay a single bill. When the driver who caused an accident has no liability insurance, there is no insurance company to pay the claim, and suing him personally can only recover what he actually owns.
Texas requires liability coverage, and the required amounts are low even when a driver carries it. Our guides on who covers the bills after an uninsured driver causes a crash and the state’s minimum coverage lay out both questions. Here, the answer sat in her own policy.
Uninsured Motorist and PIP Come With the Policy
Under Tex. Ins. Code § 1952.101(b), an insurer may not issue an auto liability policy in Texas “unless the insurer provides uninsured or underinsured motorist coverage in the policy or supplemental to the policy.” Subsection (c) lets any named insured turn the coverage down, but only in writing. That is why her own uninsured motorist claim was the first thing we looked at.
Personal injury protection follows the same rule. Section 1952.152(a) requires it, and (b) says the rule does not apply “if any insured named in the insurance policy rejects the coverage in writing.” Under § 1952.151, PIP pays “all reasonable expenses” from an accident, including necessary medical and hospital services and “replacement of income lost as the result of the accident.”
Our PIP guide explains that PIP pays whoever caused the crash, with $2,500 per person as the minimum. That lets it pay out early, before the injury claim is finished.
Starting With the Declarations Page and Keeping the Terms in Writing
With no insurer on the other side, the work centered on her policy. These are the steps we follow in a case like this.
Find the policy
The declarations page shows whether UM and PIP are on the policy and for how much. When a client cannot locate theirs, someone on our intake team will request a copy, so the coverage question is answered before anything is assumed.
Look for a signed rejection
Both coverages stay on the policy until someone named on it turns them down on paper. When nobody remembers declining PIP or UM, we have the insurer show us the signed form, since a rejection only counts in writing.
Set the terms in writing
Our fee agreement spells out the percentage, which case costs may be charged and how any liens will be handled, and the client has all of it in writing before signing.
Explain each step
Each demand is shared with the client as it goes out, along with the figure it asks for. Before any offer is accepted, the client sees every deduction that will come out of it.
$32,500 From Her Own Coverage Before Any Lawsuit Was Filed
$32,500
Total from her own UM and PIP coverage
That $32,500 is a gross figure, and the attorney fee and case expenses were taken from it first. Her result reflects her own crash and her own policy, so it says nothing about what someone else will recover.
Three Takeaways About Your Own Policy
- Check your declarations page for UM and PIP now, before you need them. In Texas both come with an auto policy and stay there until someone named on it declines them on paper.
- A driver’s admission and a deputy’s report prove fault, but they cannot pay a claim when no insurance stands behind them. Her UM coverage could, and it paid all $30,000.
- PIP paid $2,500 without regard to fault, so it can arrive early. Our Texas car accident lawyers will go through your policy with you if the car that hit you was uninsured.
Attorney Review
Reviewed by: Josh Alexander, Founder and Managing Attorney
Published and reviewed on
Other Texas Case Results Built on the Coverage That Was There
- $15,000,000I-45 truck crash wrongful deathSettled in litigation
- $5,000,000Northlake forklift wrongful deathSettled in litigation
- $850,000Pasadena red light crashSettled in litigation
- $600,000Rockwall County five vehicle crashSettled in litigation
- $600,000Mesquite 18 wheeler crashTruck accident settlement
- $325,000Hood County commercial truck crashSettled in litigation
- $175,000Round Rock construction vehicle crashSettled before suit
- $130,000Redwater head on, two limitsBoth limits, before suit
- $125,000Brownsville armored truck rear endSettled before suit
- $105,000Texas highway unsafe lane changeSettled before suit
- $105,000Three vehicle crash in DallasPolicy limits recovery
- $100,000Rear end, no police reportSettled before suit
- $95,000Midland company truck left turnSettled before suit
- $89,000San Antonio 3 car chain reactionSettled before suit
- $85,000Farmers Branch left turn, UIMSettled in litigation
- $82,500Plano company truck left turnSettled in litigation
- $80,000Jersey Village U turnSettled in litigation
- $60,000San Antonio rear end, UIMTwo policy limits, pre litigation
- $60,000Fort Worth trailer hitch rear endTwo limits, before suit
- $60,000DeSoto stop sign, broken wristTwo limits, before suit
- $50,000Allen rear end crashPolicy limits settlement
- $50,000La Porte red light T boneFull policy limit, before suit
- $30,000San Antonio rotator cuff tearPolicy limit, before suit
- $30,000Houston hit and run recoveryUM policy limits
- $30,000Richardson apartment exit crashPolicy limits, pre litigation
09Contact
Rear Ended by an
Rear Ended by an
Uninsured Driver?
Send us your crash report or your declarations page, and we will check the UM and PIP coverage on your policy. You get our fee terms in writing before you decide anything.
No fee unless we recover · Se habla español · Proudly Serving All of Texas